Because of the global nature of our economy, the world has become a much smaller place. You may therefore find yourself speaking more and more often to predominantly foreign audiences. This will necessitate learning a new set of ground rules for each country and each cultural segment you are addressing.
Legal Knowledge Center
No matter how experienced a speaker you are, rehearsals are necessary each time you make a presentation.
Preparing for a seminar is not only hectic and time-intensive, it can also be incredibly stressful for the organizers. It's inevitable that something will go wrong. But you can stay ahead of the game and maximize the number of things that go right with some careful planning.
This is the final article on conducting a due diligence review when purchasing a business. This article lists relevant records, contracts, financing and credit arrangements, and brokerage commissions relevant to the transaction.
VI. Administrative Records.
"Administration" includes all of the procedures, policies and records related to the day-to-day operations of the company. A well-run company keeps good, thorough, accurate records. You will need to review copies of all the administrative records, including:
- All current contracts with suppliers. Do any of the contracts require written notice if control of the company changes?
- All current contracts with consultants, independent contractors, commissioned sales people, etc.
- Details of trade and accrued liabilities, including payment terms.
- Inventory valuation, turnover and obsolescence review.
- Details of bank indebtedness and long-term debt.
- Insurance coverages - who or what covered, amounts, names of insurers: key man, life, health, liability, property, business interruption, product liability, etc.
- Insurance claims incurred but unreported.
- Credit reports.
- General, administrative and factory overhead.
- Backlog and order records.
- Pricing policies.
- Bank accounts.
- Government and non-government financial assistance.
- Trade association memberships, club memberships, etc. - amounts, due dates, benefits.
- Non-competition, confidentiality and nondisclosure, non-circumvention agreements.
- Management organizational chart, list of managers and department heads and functions of each.
- Employee handbooks, guidelines, workplace policies and bulletins, occupational health and safety guides.
- Employment contracts, key personnel files, confidentiality and indemnification agreements.
- Incentive plans, bonus payments, benefits packages, severance pay policy, early retirement options.
- Labor union agreements and recent negotiations.
- Worker's compensation, insured and self-insured plans.
ASSETS AND LIABILITIES
VII. Property.
Get a list of all property (real and personal) owned or leased by the business, and review all documentation related thereto.
Real Estate
- Description, location and character of all real estate property owned by the business.
- Surveys, appraisals, certificates of title, title opinions, title insurance, and inspection reports. Consider whether an inspection is required.
- Liens for taxes or assessments (if any).
- Mortgages registered against property owned by the business.
- Zoning restrictions.
- For all leased real property, name of landlord, location and condition of premises.
- Lease provisions, particularly:
- amount of rent,
- type of lease (e.g. net lease),
- permitted use,
- services and amenities included,
- right to sublease or assign,
- actions constituting breach or default,
- registration of leasehold interest on title.
Tangible Personal Property
- List of all machinery and equipment owned, leased or on order, including motor vehicles, manufacturing plant, computer systems, data processing and communications systems.
- Details of all fixed asset purchases and a schedule of depreciation.
- Conditional sales contracts, chattel mortgages or other liens.
- Terms of leases:
- payments,
- expiry dates,
- renewals (automatic or requiring notice),
- buy-out options,
- replacement and repair provisions,
- breach and default,
- discharge of lessor's security interest on purchase by lessee.
- Service agreements.
- Computer security and disaster recovery procedures.
Intangible Personal Property
- Patents, copyrights, trade names and trade marks (domestic and foreign).
- Nondisclosure agreements, trade secret agreements.
- Business licenses.
- Other licenses for company or employees.
- Ownership of subsidiaries (shares, partnership, other).
VIII. Financings.
Review all loan and credit agreements, and any other documentation evidencing material borrowing, including:
- Promissory notes.
- Letters of credit.
- Guarantees.
- Line of credit agreements.
- Sale or lease-back arrangements.
- Installment purchases.
- Correspondence with lenders for the past 3 years (or less, if the company hasn't been in existence that long).
- Any business conduct restrictions, restrictions on acquisitions or mergers, due on sale clauses.
- Conditions of breach or default.
- After-acquired property clauses in mortgage documents.
- License, franchise and royalty agreements.
IX. Broker.
Lastly, is there a broker involved in the purchase and sale transaction? Who is the broker representing? If you're liable for paying any portion of the broker's commissions and other costs, you must have a copy of the broker agreement.
Once you have had a chance to answer all of the questions and review all of the materials listed in these last few articles, you should know all you need to know to determine whether to go ahead with purchasing the business. If you and your lawyer and accountant are happy, it's time to negotiate the Purchase and Sale Agreement.
In our last post we discussed the importance of a due diligence review when you're considering purchasing a business, and covered the questions that should be answered with respect to the business' financial and corporate history. This week we talk about legal and regulatory matters, customers, goodwill, market share and potential for growth.
Today we start a 3-article series on how to conduct a due diligence review when you are considering buying an existing business. Part I of the series covers the financial, corporate and historical data you should look at with your accountants and your lawyer. If you're thinking about purchasing a business, there are many issues you need to consider and many documents you need to review with your legal and financial advisers before you close the deal. It's not only important to know the current status of the business, but also its past history, its long-term viability, future market opportunities, and potential for growth.
Congratulations! You've finally found an ideal location for your business, and you can start negotiating the lease with the landlord.
But what should you be looking for in the commercial lease agreement? Before you sign anything, review the lease and make sure it answers each of the following questions:
- Will you be given a copy of the building inspection report? If not, can you arrange for your own inspection?
- Is a drawing of the leased premises attached with the demised area clearly marked?
- What is the date of possession? What are your remedies if the space is not available to you on the date of possession?
- Are you required to obtain any approvals or comply with any local regulations or ordinances before you can commence business in the leased premises?
- How long is the rent-free period? When do the lease payments begin?
- How will your security deposit be handled? How long will it take to receive a refund of the deposit at the end of the lease term?
- Are there restrictions on your use of the space? What are those restrictions?
- What are the provisions for rental increases? How much prior notice will be given?
- Are tenants required to pay a portion of the property taxes for the building?
- What types of insurance coverage, in what amounts, are you required to carry?
- Which utilities and services will you be responsible for paying?
- What other costs are associated with the space (advertising, merchant association dues, etc.)?
- How much will the landlord pay towards your leasehold improvements?
- Are there any restrictions on what kind of signage you can have? Do you need to get the landlord's prior approval before installing your signs?
- What are the landlord's obligations for repairs and maintenance on the building, the common areas and your premises?
- How much are your common area maintenance costs?
- What are the provisions for renewal of the lease at the end of the term?
- Do you have the right to assign the lease or sublease any of the space?
- What are your rights in the event of eminent domain, foreclosure, or partial or total destruction of the premises?
- What happens if you default in any of your obligations?
- What are your remedies if the landlord defaults?
- Are you required to return the premises to its original condition at the end of the lease period? Based on the original condition, what will the costs be to do this?
- Is there an obligation to pay legal fees and costs in the event of a dispute?
If you are satisfied with the answers you get to these questions, you should submit a Letter of Intent (LOI) or a Lease Proposal to the landlord which sets out all the negotiable elements of the lease.
The LOI or proposal should set out such details as square footage, initial term, renewals, base rent, rent-free period, allowance for leasehold improvements, etc., as well as the relevant tone of your negotiations to date. This will allow the parties to continue to negotiate the final terms of the lease. Keep every draft as a paper trail documenting the negotiations.
Finally, have your lawyer review the lease BEFORE you sign. And never sign anything that you don't fully agree with.
Image by H. Cuthill
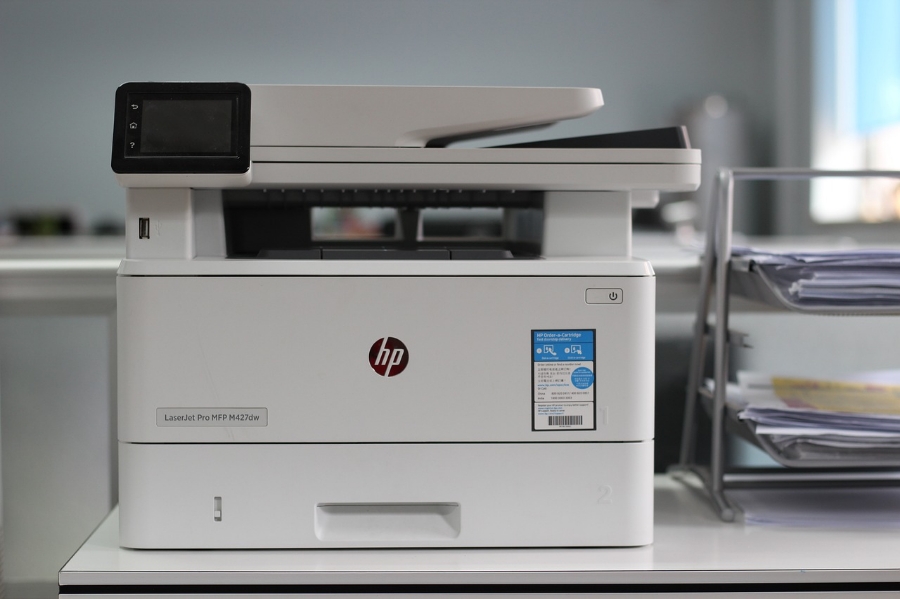
When you're starting up a business, cost drives every decision you make. And when it comes to business equipment, you need to determine whether it is most cost-effective and advantageous to lease or purchase the equipment necessary to your business.
There are essentially three options available for acquiring the equipment you need: (1) a straight lease, (2) lease-to-own (also called a finance lease), or (3) outright purchase. The term "business equipment" can apply to anything you need for your operations, including computers, printers, and other electronics; office furniture; communications systems (smartphones, pagers, etc.); alarms and security systems; shelving and storage; specialized machinery; warehouse forklifts and loaders; and vehicles.
The Pros of Leasing
The upside of leasing is that it requires less of an initial outlay than purchasing, so you're not tying up so much money right off the bat. And for computer equipment, it can be the best option.
Your lease costs can be deducted as an operating expense, and they don't depreciate. Since the average equipment lease runs for 3 years, your lease will be expiring right about the same time that your computer equipment is obsolete, and you can upgrade to a new system under a new lease. (Review the lease terms to make sure they provide for maintenance, updates and support.)
The Cons of Leasing
Your overall costs are almost always higher because of interest and fees, you don't own the assets, and you build no equity in the equipment.
In addition, the lease agreement will contain restrictions on how you use the equipment: such as whether, and how much, you can customize the equipment for your business.
Comparison of Pros and Cons
LEASING | BUYING |
Lower upfront costs have less impact on cash flow | Higher initial investment required |
Higher total costs overall, interest rates much higher on lease than financed purchase | Lower total investment over the life of the equipment |
No ownership or equity until end of term | Ownership of and equity in assets upon purchase, with option for resale |
Easy upgrade options during and at end of term | Full control over use and customization of equipment |
Maintenance and insurance can be added as option to lease | Maintenance and insurance costs must be fully covered by owner |
Lease costs can be deducted as operating expenses | Equipment can be depreciated over a period of years which can be a tax benefit, but can mean loss of value |
Fixed monthly payments which can end up costing more than the value of the equipment over the term of the lease | Large upfront cost, but fewer ongoing expenses |
Penalties for early termination |
|
Should I Buy Instead?
When you buy it, you own it. And you can probably deduct a good portion of those asset purchases on your business income tax return. You also get the benefit of the depreciation deduction. If the equipment you need has a lifespan of more than 3-5 years and you've got the capital to do it, you probably should purchase instead of leasing it.
Office furniture is a good example of equipment with a long lifespan. While you may replace the chairs every few years, it's likely that the desks, shelving and filing cabinets will be around for a long time. These items are readily available from second-hand office suppliers, which can save you money. Buying second hand can be a great way to save money and still get what you need. Look for classified ads, listings on Craig's List and Kijiji, and shops that specialize in used office equipment and supplies.
Check out the local and online auctions as well. You have more recourse when buying from a dealer since you can usually take the item back, although there will probably be no warranty. The price might be higher than if you bought it from an individual, but the ability to return the item is worth paying more for. The risk you run when buying from an auction is that you can't actually test the equipment beforehand. Many auctions sell goods as seen, which means if the goods do not work, you have almost no chance of getting your money back, except for online auctions such as eBay. Find out what the restrictions are - and what your rights are - before bidding on any auction items.
Determining the Actual Costs
Many start-up companies will need to finance any equipment purchases. There are some questions that you will have to get answered in order to determine what the actual cost of leasing versus purchasing will be.
- What is the required down payment for the equipment?
- What is the term of the lease or loan?
- What are the monthly payments?
- What is the interest rate?
- Is there a final balloon payment at the end of the term? If so, what is the amount?
- What is the cost of an extended warranty (if applicable)?
- If lease-to-own, can you buy out early? At what cost?
- What is the total cost of the lease or loan (including maintenance and warranties) over its lifetime?
- If leasing to own, how much more are you paying to lease the equipment over and above its actual value?
- What are the tax deductions available if you purchase?
- What would the resale value of the purchased equipment be?
Can You Afford It?
Now that you know what the costs will be, ask yourself whether the business can afford it? Do you have sufficient cash flow at present to support your monthly lease or loan payments? If your business is seasonal, you'll need enough cash to support those payments during your off-season. And what about the maintenance costs? Are they included in your lease? Did you provide for them in the loan calculations? Do you know what they are? Then there's insurance. How much is the annual insurance cost to cover the equipment? Is it included in the lease?
If the answer to any of the above questions is "No", you should determine which equipment is absolutely essential for your business, and which items can wait until your cash flow improves. If you have to have it and the cash isn't there to buy it, then talk to several leasing companies and negotiate the best lease you can.
Image by xuefei wang from Pixabay
- 2026
- 2025
- 2024
- 2023
- 2021
- 2020
- 2019
- 2018
- 2017
- 2016
- 2014
- 2013
- 2012
- 2011